Retirement may free up your calendar, but it does not always free you from rising expenses. A few unexpected bills can make a fixed monthly budget feel tighter than planned.
Yet returning to a full-time schedule can defeat the reason you retired. The better option may be part-time work that pays well in retirement without claiming every weekday.
Some jobs reward decades of experience, while others pay for practical skills or a few focused weeks of effort. These nine options show what the work involves, what the numbers mean, and where the financial tradeoffs hide.
How Much Can These Retirement Jobs Actually Pay?
The biggest mistake is comparing hourly rates without considering how much work is available. Someone earning $60 an hour for 10 hours a week could collect $24,000 over 40 working weeks, while a specialist charging $500 an hour might receive only a handful of assignments.
Here is a quick look at the nine opportunities. Some figures represent employee wages, while others are business charges or professional fees rather than take-home income.
| Part-Time Job | Published Pay or Fee Benchmark | Main Consideration |
|---|---|---|
| Former-employer consultant | Negotiated contract rate | Requires relevant experience |
| Expert witness | $450/hour median file-review fee, 2024 survey | Specialized expertise |
| Educational content creator | No reliable standard hourly income | Audience and customer development |
| Independent handyman | $50–$150/hour in customer labor charges, 2026 | Expenses and licensing |
| FINRA arbitrator | $600 per standard hearing day | Limited assignments |
| Seasonal tax preparer | $26.40/hour median employee wage, 2025 | Concentrated tax-season work |
| End-of-life doula | $50–$80/hour at one regional provider group | Irregular private-client demand |
| Professional line stander | Roughly $18–$25/hour in one platform’s advertised pilot rates | Location-dependent demand |
| Insurance claims adjuster | $37.51/hour occupational median, May 2025 | Catastrophe assignments vary |
These numbers are not promises of income. The best retirement job depends on how often it pays, what it costs to perform, and how much freedom remains after accepting the work.
1. Return to Your Former Employer as a Consultant
One of the most valuable retirement opportunities may be waiting at the company you recently left. Years of experience often mean knowing systems, clients, and procedures that newer employees have not yet learned.
When an experienced worker retires, the organization sometimes discovers that replacing a job title is easier than replacing institutional knowledge. A former employee may then return for limited consulting assignments without accepting a full-time schedule.
Consider a hypothetical retiree who previously earned about $48 an hour as an employee. If that person negotiates a consulting fee of $75 an hour and works 10 hours weekly for 40 weeks, gross annual billings would reach $30,000.
That can be attractive compared with returning to a regular position. However, consultants generally must cover their own business expenses and do not automatically receive employer-funded benefits.
The opportunity: Former employees may be hired to train new staff, troubleshoot systems, document procedures, oversee special projects, or advise managers. Some work can be performed remotely, depending on the employer and industry.
The smartest approach is to contact former managers before searching for entirely new clients. Ask whether the organization needs occasional assistance with projects where your existing knowledge would shorten the learning curve.
Retirees with traditional pensions should also check their plan’s return-to-work provisions. Some pension arrangements have special rules governing reemployment, benefit payments, or working for the former employer.
2. Become an Expert Witness and Get Paid for Specialized Knowledge
A retired engineer, accountant, nurse, contractor, or medical professional might possess expertise that becomes valuable during a legal dispute. Attorneys sometimes hire independent experts to review evidence, explain professional standards, and offer opinions within their field.
This work can command impressive fees because clients are paying for specialized judgment rather than routine labor. However, it generally requires demonstrable credentials, experience, and the ability to explain technical findings clearly.
SEAK’s 2024 Expert Witness Fee Survey reported substantial compensation among participating professionals. Its published median figures were $450 per hour for file review and preparation, $475 for depositions, and $500 for courtroom testimony.
Those figures describe surveyed expert witness fees, not what every new expert can earn. Many retirees will never qualify for this work, and even established professionals may have long gaps between paid cases.
A useful comparison shows why expertise can have different financial values depending on how it is sold.
| Work Arrangement | Hypothetical Workload | Gross Revenue |
|---|---|---|
| Part-time employee | $40/hour, 10 hours weekly, 40 weeks | $16,000 |
| Independent consultant | $75/hour, 10 billable hours weekly, 40 weeks | $30,000 |
| Expert witness | $450/hour, 20 billable hours annually | $9,000 |
| Private instructor | $100 per session, 10 paid sessions | $1,000 |
The comparison reveals an important distinction. A higher hourly fee does not necessarily produce greater annual income when paid assignments are scarce.
Expert witness work also involves professional responsibility. Experts need to remain impartial, protect confidential information, maintain appropriate credentials, and recognize that some cases require depositions or courtroom appearances.
Retirees interested in this field can begin by identifying their strongest area of professional knowledge. They can then investigate established expert witness directories and the requirements attorneys place on specialists in that industry.
3. Teach Your Professional Knowledge Through Online Content
Some retirees have decades of valuable knowledge but no interest in returning to their former workplace. Creating educational videos, online lessons, or professional training materials offers another way to use that experience.
A retired mechanic could explain common vehicle problems, while a former accountant might teach small-business bookkeeping. Experienced managers could provide practical lessons on hiring, workplace communication, or project planning.
The internet makes it possible to reach people without opening a physical classroom. However, building an audience and attracting paying customers usually requires more time than successful creators’ stories suggest.
The main financial opportunity is not limited to advertising revenue. Educational content may introduce viewers to paid workshops, consulting services, instructional products, or coaching sessions.
Imagine a retired professional who develops a focused training workshop priced at $150 per participant. Selling 12 places would generate $1,800 in gross revenue before platform charges, marketing expenses, and preparation costs.
That example illustrates a possible business model rather than an expected result. Many new content creators earn nothing initially, and some never develop a dependable source of income.
Retirees should begin with a subject they understand deeply and a problem people genuinely want solved. Creating a small collection of useful lessons is a more reasonable first step than spending retirement savings on expensive production equipment.
4. Offer Handyman Services for Small Home Repairs
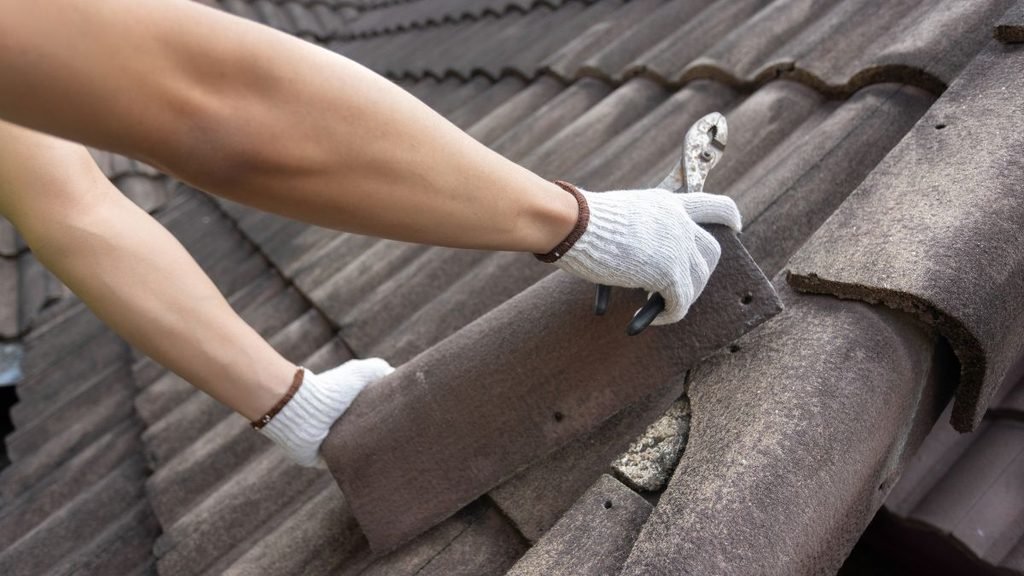
People who enjoy repairing things around the house may have a practical way to generate retirement income. Homeowners regularly need help with loose cabinet doors, damaged drywall, shelving, furniture assembly, and other smaller maintenance jobs.
Independent handyman businesses can charge more than many people expect. Angi’s 2026 pricing information describes customer labor charges of roughly $50 to $150 an hour, depending on the location, task, and provider.
Those customer prices are very different from employee wages. The Bureau of Labor Statistics reported a median wage of $23.84 an hour for general maintenance and repair workers in May 2025.
An independent worker charging $80 an hour for six billable hours weekly over 46 weeks would collect $22,080 in annual gross revenue. The actual profit would be lower after tools, materials, insurance, transportation, advertising, and other business costs.
The best strategy may be smaller, repeatable jobs rather than major renovations. A retiree who becomes known for dependable minor repairs could develop relationships with homeowners, landlords, and property managers.
Bundling several small tasks into one appointment may also improve earnings. It reduces the number of unpaid trips and estimates needed to produce a reasonable day’s revenue.
Licensing is a serious consideration. Some states and local governments limit what unlicensed handyman businesses can perform, particularly electrical, plumbing, gas, roofing, and other regulated work.
Physical demands matter as much as earning potential. Retirees should select tasks that fit their abilities and avoid ladders, heavy lifting, or hazardous work that could create unnecessary risks.
5. Become a FINRA Arbitrator Without Being a Lawyer
One of the less familiar retirement jobs involves helping resolve disputes between investors, brokerage firms, and other parties. The Financial Industry Regulatory Authority, commonly called FINRA, uses arbitrators to hear evidence and make binding decisions in securities disputes.
The surprising part is that applicants do not need previous experience as lawyers or securities professionals. FINRA recruits qualified people from a range of professional backgrounds.
Under its current eligibility requirements, new applicants generally need a four-year college degree and at least five years of full-time paid professional experience. Accepted applicants must also complete FINRA’s arbitrator training and assessments.
FINRA states that arbitrators typically receive $600 for a full hearing day. Qualified chairpersons may receive $850 for a hearing day, while prehearing conferences typically carry a $300 honorarium.
Those payments can be attractive for occasional intellectual work. However, retirees should not confuse a $600 daily payment with steady employment.
FINRA explains that an arbitrator might receive one or two cases annually, and assignments can be even less frequent. Selection depends on cases, location, qualifications, conflicts of interest, and the parties involved.
The role requires careful listening, fair judgment, and the willingness to review unfamiliar disputes. Some responsibilities may be performed remotely, although hearings and related work can still require substantial preparation.
For a retiree seeking meaningful occasional assignments rather than dependable monthly income, arbitration may be worth considering. It is less suitable for someone who needs a guaranteed number of paid hours every week.
6. Prepare Tax Returns During the Busy Filing Season
Seasonal tax preparation is one of the more established ways to earn money without working throughout the year. Much of the demand is concentrated between January and April, although some preparation and filing work continues outside that period.
Employers may hire temporary workers to organize records, interview clients, prepare returns, and assist with tax software. The responsibilities depend on training, experience, and the employer’s requirements.
According to May 2025 Bureau of Labor Statistics wage data, tax preparers earned a national median hourly wage of $26.40. Experienced preparers and people operating their own businesses may have different earnings, but independent work also brings additional responsibilities.
A retiree earning that median wage for 20 hours per week over 12 weeks would receive approximately $6,336 before taxes. That could provide a useful income boost without requiring a year-round commitment.
Running a private preparation business introduces another financial model. The owner generally charges clients per return or by service, but must also pay for software, security, administration, and customer acquisition.
The following figures show how the same seasonal opportunity can produce different gross totals.
| Tax Preparation Scenario | Assumption | Gross Seasonal Revenue |
|---|---|---|
| Part-time employee | 15 hours weekly, 12 weeks, $26.40/hour | $4,752 |
| Busier seasonal employee | 20 hours weekly, 12 weeks, $26.40/hour | $6,336 |
| Independent preparer | 75 returns at an assumed $200 each | $15,000 |
| Larger private workload | 125 returns at an assumed $200 each | $25,000 |
The independent examples are hypothetical, not published average earnings. A private preparer would need enough customers, suitable training, and the ability to complete each return correctly and securely.
Paid federal tax return preparers generally need an active IRS Preparer Tax Identification Number, or PTIN. The IRS lists a PTIN application or renewal fee of $18.75 for 2026 and 2027, while some states impose additional registration or education requirements.
Having a PTIN does not automatically make someone competent to prepare every type of return. Beginners should obtain proper training and consider starting with supervised seasonal employment before accepting independent clients.
7. Work as an End-of-Life Doula Supporting Families
Some retirees prefer work that offers personal meaning alongside financial compensation. An end-of-life doula provides nonmedical emotional, practical, and informational support to people approaching death and to their families.
The work can involve companionship, listening, helping families organize arrangements, and offering a calm presence during difficult moments. End-of-life doulas do not replace hospice nurses, physicians, or other licensed healthcare professionals.
The National End-of-Life Doula Alliance explains that compensation varies widely. Some doulas charge hourly fees or offer packages, while others volunteer or use sliding-scale rates.
For example, the Colorado End-of-Life Collaborative reports that doulas within its group charge approximately $50 to $80 an hour. That is a regional illustration rather than a verified national wage average.
At an assumed $60 hourly fee, eight paid hours in a week would produce $480 in gross revenue. Yet client demand can be unpredictable, and many families need intensive support for a short period rather than regular appointments over several months.
Training can help retirees understand ethical boundaries, communication techniques, and practical end-of-life support. Some programs offer certificates, but there is no single universally recognized national licensing system for the occupation.
Emotional readiness is as important as financial potential. This work can involve grief, demanding family situations, and irregular hours that may include evenings and weekends.
Former healthcare workers, social workers, caregivers, and people with relevant volunteer experience may find the role especially meaningful. Anyone considering it should understand the nonmedical scope of practice, local requirements, liability considerations, and the importance of respecting each family’s wishes.
8. Get Paid to Wait in Line for Other People
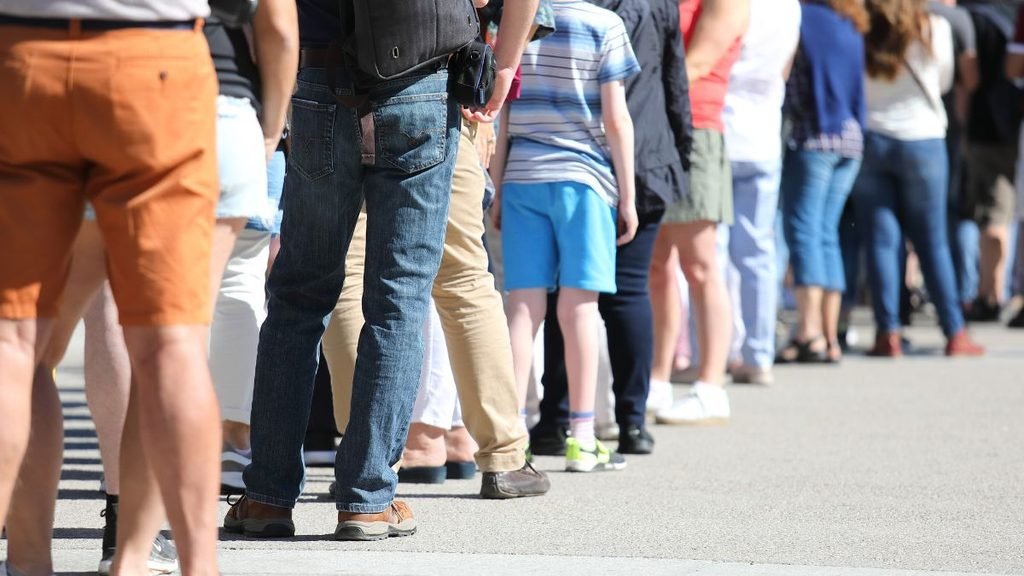
Professional line standing sounds unusual, but it is a real service in some communities. Customers pay someone else to wait for limited-release products, tickets, restaurant openings, or other appointments where arriving early provides an advantage.
The work requires relatively little formal training. Reliability, punctuality, communication, and the ability to follow instructions are usually more important than professional credentials.
Pay varies considerably by location and platform. One line-standing platform advertises pilot worker rates that generally work out to about $18 to $25 per hour, while services such as Taskrabbit allow providers to set their own rates.
An independent worker who completes nine paid hours weekly at $22 an hour would collect $198 before expenses. Over 30 active weeks, that would amount to approximately $5,940 in gross earnings.
That is meaningful supplemental income, but it depends on successfully finding enough assignments. Some workers may receive only occasional requests, while others in busy urban markets could encounter more opportunities.
Location is the biggest limitation. Professional line standing is more practical where restaurants, events, public offices, or product launches create regular waiting periods.
Customers and venues may also have rules against transferring places in line. Workers must confirm that the service is permitted rather than assume that every queue allows paid substitutes.
Weather, early mornings, transportation costs, and long periods on one’s feet can reduce the job’s appeal. Retirees who prefer occasional outdoor work might enjoy it, while those seeking predictable hours or less physical strain may find better options elsewhere.
9. Work as a Catastrophe Insurance Claims Adjuster
When major storms, floods, hail damage, or other disasters affect large areas, insurers may need additional people to examine claims. Some companies and independent adjusting firms use temporary or contract adjusters when claims volume increases.
The work can involve inspecting property damage, documenting losses, reviewing policies, preparing estimates, and communicating with policyholders. Certain assignments require travel, while others may emphasize desk-based review or documentation.
The Bureau of Labor Statistics reported a median wage of $37.51 per hour for claims adjusters, examiners, and investigators in May 2025. That occupational benchmark covers a broad group of employees and should not be treated as the typical pay for independent catastrophe assignments.
Independent adjusters may instead receive compensation based on fee schedules or completed claims. Their gross revenue can look substantial during busy deployments, but travel, lodging, equipment, licensing, and periods without assignments can materially reduce annual earnings.
For example, a hypothetical contract paying $250 per completed claim would produce $5,000 in gross revenue for 20 claims. That calculation does not establish how many claims a new adjuster can complete or whether the workload will be available.
Some retirees may prefer less physically demanding assignments, including contents inventories, document reviews, or desk adjusting. However, those positions still require suitable training, technical knowledge, and employer approval.
State licensing requirements vary, and some jurisdictions provide temporary catastrophe-related authorizations under specific conditions. Applicants should consult their state insurance department and understand whether they are seeking staff, independent, or emergency adjusting work.
This opportunity is best suited to retirees who can tolerate uncertain schedules and occasional concentrated workloads. Someone who needs dependable monthly income should be cautious about relying on weather-related assignments.
What Could Part-Time Retirement Work Add to Your Annual Income?
Hourly compensation matters, but annual income depends on the number of hours that actually produce payment. High-fee assignments may look impressive on paper without generating enough work to support a household budget.
The following scenarios use stated assumptions rather than guaranteed job-market outcomes. They illustrate how a modest weekly schedule can affect retirement cash flow.
| Work Scenario | Assumed Paid Schedule | Gross Annual Income |
|---|---|---|
| Consulting | $60/hour × 10 hours × 40 weeks | $24,000 |
| Handyman services | $80/hour × 6 billable hours × 46 weeks | $22,080 |
| Seasonal tax work | $26.40/hour × 20 hours × 12 weeks | $6,336 |
| Professional line standing | $22/hour × 9 hours × 30 weeks | $5,940 |
These are gross figures, not take-home earnings. The consulting, handyman, and line-standing scenarios may require business expenses and unpaid administrative time that reduce actual profits.
A retiree should also consider how extra earnings interact with Social Security, income taxes, pension arrangements, and Medicare premiums. A larger paycheck does not always translate into the same increase in money available to spend.
How Part-Time Work Affects Social Security in 2026
Retirees sometimes avoid working because they believe Social Security will permanently take away their benefits. The actual rules depend primarily on whether they have reached full retirement age and how much they earn.
For 2026, the Social Security Administration applies the following retirement earnings test limits. The rules concern benefit withholding, not a maximum amount that people are legally allowed to earn.
| Retirement Status in 2026 | Earnings Limit | Effect on Benefits |
|---|---|---|
| Below full retirement age all year | $24,480 | $1 withheld for every $2 above the limit |
| Reaching full retirement age during 2026 | $65,160 before that month | $1 withheld for every $3 above the limit |
| At or above full retirement age | No earnings limit | No retirement benefits withheld under the earnings test |
Consider a hypothetical retiree who remains below full retirement age throughout 2026 and earns $30,000 from work. That is $5,520 above the annual limit, potentially resulting in $2,760 of Social Security retirement benefits being withheld.
Those withheld benefits are not necessarily lost permanently. Once the person reaches full retirement age, Social Security recalculates benefits to account for months when payments were reduced or withheld because of the earnings test.