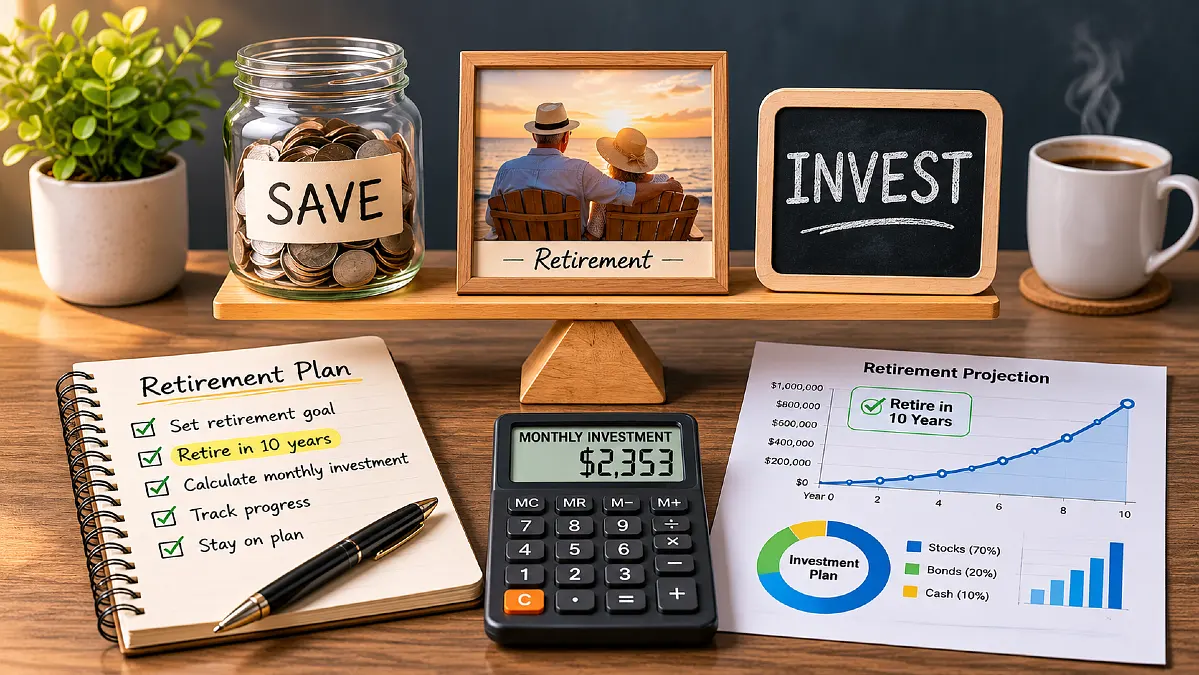
Ten years may sound like enough time to build a retirement fund. But how much you need to invest monthly to retire in 10 years can be much higher than expected.
Someone spending $3,000 a month today could need more than $4,000 for the same lifestyle in 2036. That difference can make a seemingly reasonable savings goal much harder to reach.
The answer also depends on your existing savings and future Social Security benefits. The following calculations reveal what it could actually take to retire within a decade.
The Monthly Investment Number Most People Underestimate
Suppose someone wants to retire in 2036 and maintain a lifestyle that costs $3,000 monthly today. Starting with no savings, that person could need to invest approximately $7,400 every month.
This calculation assumes 6% annual investment growth after fees and 3% yearly inflation. It also assumes the retirement portfolio must cover every expense without Social Security or pension income.
That number is much higher than the $3,000 to $4,000 monthly investment often suggested in simple retirement examples. However, it does not mean everyone needs to save $7,400.
Someone with $400,000 already invested could reach the same projected target by contributing approximately $2,940 monthly. Existing retirement savings make an enormous difference because they have another decade to grow.
The important lesson is that monthly contributions are only one part of the equation. Your starting balance, retirement expenses, investment returns, and other income sources determine the actual target.
How Much Money Does It Take to Retire in 10 Years?
Before calculating monthly investments, determine how much money you expect to spend after retiring. Housing, groceries, transportation, insurance, healthcare, and personal expenses should all be included.
Someone spending $3,000 monthly needs $36,000 annually in today’s dollars. Using the traditional 4% starting withdrawal guideline, that spending would suggest a retirement portfolio of approximately $900,000 today.
The calculation divides annual spending by 0.04 to estimate the investment balance needed. However, this is only an initial planning guideline, not a guarantee that the money will last.
The problem is that retirement begins 10 years from now. With 3% annual inflation, today’s $3,000 monthly lifestyle could cost approximately $4,032 in 2036.
That pushes the estimated retirement portfolio target to approximately $1.21 million. Building that amount from zero in 10 years requires substantial monthly investments.
| Monthly Spending Today | Portfolio Needed in 2036 | Monthly Investment Needed |
|---|---|---|
| $1,500 | $605,000 | $3,690 |
| $2,000 | $806,000 | $4,920 |
| $2,500 | $1,008,000 | $6,150 |
| $3,000 | $1,210,000 | $7,380 |
| $4,000 | $1,613,000 | $9,840 |
These hypothetical estimates assume 6% annual investment growth after fees, 3% annual inflation, and 10 years of monthly contributions. They also assume no starting savings and a 4% initial withdrawal rate.
The table reveals how strongly retirement spending affects the amount you must invest. Someone planning to spend $4,000 monthly today needs roughly twice the retirement savings of someone spending $2,000.
However, these calculations assume investments cover every dollar of retirement expenses. Social Security, pensions, and other dependable income can significantly reduce the investment requirement.
Why Inflation Changes the Entire Retirement Calculation
Inflation is one of the easiest expenses to overlook when planning retirement. It quietly increases the amount needed for everyday purchases, even when your lifestyle stays the same.
Suppose a household spends $36,000 annually in 2026. At 3% annual inflation, maintaining that lifestyle could cost approximately $48,381 annually by 2036.
That represents more than $12,000 in additional yearly expenses. The household would not necessarily be buying anything extra, only paying higher prices for similar needs.
Inflation also changes the meaning of investment returns. A portfolio earning 7% annually does not provide 7% more purchasing power when prices are also increasing.
With 7% investment growth and 3% inflation, the inflation-adjusted return is approximately 3.9% before any additional taxes or costs. That difference matters considerably over a decade.
This is why retirement calculations must distinguish future dollars from today’s purchasing power. A large investment balance in 2036 may buy less than the same amount would buy today.
How Different Investment Returns Change Your Monthly Target
Investment returns can make an enormous difference over 10 years. However, assuming unusually strong returns can make an unrealistic retirement plan appear affordable.
Consider someone trying to accumulate approximately $1.21 million by 2036. The monthly investment needed changes depending on the annual return earned.
| Annual Investment Return | Monthly Investment Needed | Difference From 6% Scenario |
|---|---|---|
| 4% | $8,214 | $833 more |
| 5% | $7,789 | $408 more |
| 6% | $7,381 | Baseline |
| 7% | $6,988 | $393 less |
| 8% | $6,611 | $770 less |
These projections assume no starting balance and monthly contributions over 10 years. Returns are hypothetical annual rates after fees and before personal taxes, not forecasts or guarantees.
At 4% growth, the investor would need to contribute more than $8,200 monthly. At 8%, the contribution falls to approximately $6,600.
The difference looks appealing, but higher expected returns usually involve additional investment risk. Stock market performance can vary significantly from one decade to another.
A person approaching retirement cannot assume the market will deliver strong gains exactly when needed. A major downturn near retirement could leave the portfolio well below its planned value.
Instead of depending on one optimistic projection, compare several possible outcomes. If retirement works only under the strongest return assumption, the plan may need adjustments.
What $1,000 or $1,500 a Month Can Really Build
Not everyone can afford to invest several thousand dollars every month. Smaller contributions can still build meaningful savings, especially when investments remain consistent.
Suppose someone invests $1,000 monthly for 10 years. At a hypothetical 6% annual return, the account could grow to approximately $164,000.
The investor would contribute $120,000 personally over that period. The remaining amount would come from projected investment growth.
Increasing the monthly contribution to $1,500 could produce approximately $246,000. That includes $180,000 in personal contributions and around $66,000 in investment growth.
These balances are useful, but they do not automatically provide enough income for retirement. The amount someone can reasonably withdraw matters more than the account balance alone.
Using a 4% initial withdrawal calculation, a $246,000 portfolio would provide approximately $9,840 during the first retirement year. That equals about $820 monthly before applicable taxes.
For someone expecting Social Security or pension income, that extra money could make a meaningful difference. For someone relying entirely on investments, it may fall far short.
Why Compounding Cannot Do All the Work
Compounding allows investment earnings to generate additional earnings over time. However, someone investing for only 10 years has fewer opportunities for that growth than someone investing for 30 years.
Consider an investor contributing $3,000 monthly at an assumed 6% annual return. After 10 years, the account could reach approximately $492,000.
Of that amount, $360,000 would come directly from personal contributions. Approximately $132,000 would come from projected investment growth.
The example shows why monthly savings matter so much during a shorter retirement timeline. Investors cannot depend on compounding alone to turn small contributions into a large portfolio.
How Existing Retirement Savings Change the Answer
Starting with an established investment portfolio can dramatically reduce the amount needed each month. Existing savings continue growing while new contributions are being added.
Consider two people planning to retire in 2036 with identical spending goals. One has no retirement investments, while the other already has $400,000.
Their monthly contribution requirements will look completely different. The investor with substantial savings has a much stronger starting position.
| Current Investment Balance | Projected Value in 10 Years | Additional Monthly Investment Needed |
|---|---|---|
| $0 | $0 | $7,381 |
| $100,000 | $181,940 | $6,270 |
| $250,000 | $454,850 | $4,605 |
| $400,000 | $727,760 | $2,940 |
| $600,000 | $1,091,640 | $720 |
The calculations assume a $1.21 million retirement target and 6% nominal annual growth after fees. They also assume existing savings remain invested and no withdrawals occur during the decade.
Someone starting with $400,000 would need approximately $2,940 monthly under these assumptions. Someone starting from zero would need more than $7,300.
That is why a single recommended monthly savings amount cannot work for every household. Two people with identical retirement goals may have very different financial requirements.
It is also important to distinguish investable assets from total net worth. A paid-off house may be valuable, but it does not automatically produce spendable retirement income.
Home equity may become available through selling, downsizing, or borrowing. Until that happens, it should not simply be counted as cash available for withdrawals.
Why Social Security Can Cut the Amount You Need
One of the biggest weaknesses in simple retirement calculations is ignoring Social Security. Many Americans will receive retirement benefits that reduce the amount needed from investments.
Suppose someone wants approximately $4,032 monthly in 2036 to maintain a $3,000 lifestyle in today’s dollars. Without other income, investments would need to cover the full amount.
Now assume that person expects $2,000 monthly from Social Security, expressed in 2036 dollars. The remaining amount needed from investments would be approximately $2,032 monthly.
That equals around $24,381 annually from the portfolio. Using a 4% starting withdrawal calculation, the required investment balance falls to approximately $610,000.
Starting from zero, someone could potentially reach that target by investing approximately $3,720 monthly. That is far less than the $7,380 required without Social Security.
However, Social Security benefits depend on earnings history and claiming age. A person retiring before age 62 cannot begin collecting their own retirement benefits immediately.
For people born in 1960 or later, full retirement age is 67. Claiming earlier generally reduces monthly benefits, while delaying beyond full retirement age can increase payments until age 70.
Someone planning to retire at 58 may need investments to cover several years before Social Security begins. Those additional years should be included in the retirement income plan.
The Social Security Administration provides personalized benefit estimates based on work history. Using those figures is far more reliable than assuming everyone will receive the same monthly payment.
Where to Invest During Your Final 10 Working Years
Choosing investments during the final decade before retirement requires balancing growth and risk. The goal is to build savings without exposing the entire retirement plan to unnecessary losses.
A diversified investment portfolio often includes stocks, bonds, and cash. Each serves a different purpose and behaves differently during changing market conditions.
Stocks offer long-term growth potential but can experience substantial declines. Bonds may provide income and stability, although their prices and returns can also change.
Cash reserves provide flexibility when unexpected expenses arise. They may also reduce the need to sell investments during a market downturn.
Someone retiring at 67 with a dependable pension may be comfortable taking more investment risk. Someone retiring at 50 without other income may need a different approach.
Why Investment Fees Deserve Attention
Investment fees can appear small when expressed as percentages. However, those charges reduce the amount of money available to compound over time.
Consider someone investing $1,500 monthly for 10 years. At a hypothetical 7% annual return after fees, the account could grow to approximately $260,000.
At a 6% return, the same contributions would produce approximately $246,000. That one percentage point difference translates to nearly $14,000 over the decade.
Low-cost, diversified index funds may be useful options for some investors. However, investment selection should also consider risk, asset allocation, and the investor’s retirement timeline.
How the 2026 Retirement Contribution Limits Can Help
Workers approaching retirement may have opportunities to contribute more through tax-advantaged accounts. These options become especially important for people who started saving later.
For 2026, the standard employee 401(k) contribution limit is $24,500. Eligible workers age 50 or older can generally make an additional $8,000 catch-up contribution.
Workers ages 60 through 63 may qualify for a larger $11,250 catch-up contribution. That increases their potential employee 401(k) contributions to $35,750 for the year.
| Account or Age Group | 2026 Annual Limit | Monthly Equivalent |
|---|---|---|
| 401(k), under 50 | $24,500 | $2,042 |
| 401(k), age 50 or older | $32,500 | $2,708 |
| 401(k), ages 60 through 63 | $35,750 | $2,979 |
| IRA, under 50 | $7,500 | $625 |
| IRA, age 50 or older | $8,600 | $717 |
The 401(k) amounts include applicable employee catch-up contributions but exclude employer contributions. IRA contribution eligibility and tax benefits depend on individual circumstances.
An eligible 60-year-old could potentially contribute $35,750 to a 401(k) and another $8,600 to an IRA. Together, that represents $44,350 annually, or nearly $3,700 monthly.
However, not every contribution will qualify for the same tax treatment. Income limits, plan participation, and Roth contribution rules can affect eligibility.
Certain higher-paid workers must also make 401(k) catch-up contributions on a Roth basis beginning in 2026. The applicable rule generally uses prior-year wages above the $150,000 threshold.
Employer matching contributions can further strengthen retirement savings. Workers should review their plan details to determine how much additional money their employer may contribute.
For households needing to invest beyond retirement account contribution limits, taxable brokerage accounts may provide another option. The appropriate combination depends on taxes, investment goals, and withdrawal needs.
The Risks That Could Disrupt Your Retirement Date
A retirement plan may look successful when projected returns are smooth and predictable. Actual markets rarely deliver the same investment growth every year.
One particularly important risk is experiencing large losses immediately before or after retirement. Financial planners call this sequence-of-returns risk.
Suppose someone reaches retirement with approximately $1.21 million invested. Their plan calls for withdrawing about $48,400 during the first retirement year.
If the portfolio loses 25%, its value would fall to roughly $907,000 before withdrawals. Continuing to withdraw $48,400 would now consume approximately 5.3% of the reduced portfolio.
That higher withdrawal percentage could place significant pressure on future savings. A prolonged market downturn might force the retiree to reduce spending or adjust withdrawal plans.
Healthcare Can Change Your Retirement Budget
Healthcare expenses can make early retirement more expensive than expected. Someone leaving work before age 65 generally needs a health insurance plan before becoming eligible for Medicare.
Premiums, deductibles, prescriptions, and other medical costs should be included in retirement projections. Assuming healthcare expenses will remain unchanged can create a serious budget gap.
Even after Medicare eligibility begins, retirees may face premiums and out-of-pocket expenses. Medicare also generally does not cover long-term custodial care.
Taxes Can Reduce Your Retirement Income
Traditional retirement account withdrawals are generally subject to income tax. Someone needing $4,000 monthly after taxes may need to withdraw more than that amount.
Early retirement introduces additional complications because withdrawals before age 59½ may trigger an extra 10% tax. Certain accounts and qualifying exceptions allow different treatment.
A retirement plan should therefore calculate spendable income rather than relying only on account balances. Roth accounts, traditional retirement plans, and taxable investments can have different tax consequences.
Debt Can Raise the Amount You Need
Large monthly debt payments can increase retirement spending requirements. Mortgage payments, car loans, and credit card balances may continue after employment income ends.
Eliminating a $500 monthly payment reduces annual spending by $6,000. Under a 4% withdrawal calculation, that could lower the required portfolio by approximately $150,000.
However, paying off every debt before retirement is not automatically the best choice. Interest rates, liquidity, taxes, and investment risks should guide the decision.
Five Practical Steps to Make a 10-Year Retirement Plan Work
Retiring in 10 years requires more than selecting a monthly contribution amount. A useful plan should measure progress and allow changes when income, expenses, or investment performance shift.
The following steps can help turn a retirement goal into a practical savings schedule. Each addresses a different part of the financial preparation process.
| Timeline | Main Priority | Action to Take |
|---|---|---|
| First 30 days | Calculate the gap | Estimate expenses, review investments, and check Social Security |
| First year | Increase contributions | Review the budget, employer match, and catch-up eligibility |
| Years 2 through 6 | Build momentum | Automate saving, control fees, and increase contributions |
| Years 7 through 9 | Reduce retirement risk | Review investments, debt, healthcare, and income needs |
| Final year | Test the retirement plan | Check balances, taxes, withdrawal plans, and cash reserves |
The first priority is determining how much retirement income will come from dependable sources. Subtracting that amount from expected expenses reveals what investments must provide.
Next, calculate how much the existing portfolio could grow under different return assumptions. The remaining gap determines how much additional money must be invested.
Increase Income Instead of Cutting Everything
Reducing unnecessary expenses can free up money for investments. However, households with already tight budgets may have limited opportunities to reduce spending further.
Increasing income may provide a more meaningful improvement. A promotion, career change, additional work hours, or sustainable side business could create extra money for retirement.
Someone increasing monthly contributions by $500 could accumulate approximately $82,000 from those additional investments over 10 years. That assumes a 6% annual return and consistent monthly contributions.
The additional income does not have to support a more expensive lifestyle. Directing part of it toward retirement savings can strengthen the long-term plan.
Make Monthly Investments Automatic
Automatic contributions reduce the need to make the same savings decision every month. Workers can direct money from each paycheck into retirement accounts before spending it elsewhere.
This approach can be especially effective when earnings increase. Raising contributions alongside salary increases may help prevent lifestyle spending from absorbing all additional income.
However, automatic investing should not mean ignoring the portfolio. Retirement accounts still need periodic reviews for fees, risk, asset allocation, and progress.
Reconsider the Retirement Date When Necessary
Some households will discover that their ideal monthly investment target is beyond their current budget. That does not mean every retirement goal must be abandoned.
Working an additional year or two may provide more time for contributions and investment growth. Delaying retirement can also reduce the number of years investments must support household spending.
Partial retirement may offer another practical option. Working fewer hours while receiving some employment income can reduce the amount withdrawn from savings.
A retirement date should be treated as a financial goal rather than an unchangeable deadline. Adjusting that date may create a more sustainable retirement plan.